"KwaZulu-Natal's level 4 storm warning: Your blocked gutter could cost you the claim"
SAWS raised KwaZulu-Natal to a level 4 storm warning. Here is exactly which policy pays when hail, flood or lightning hits, and the one habit that can sink a claim.
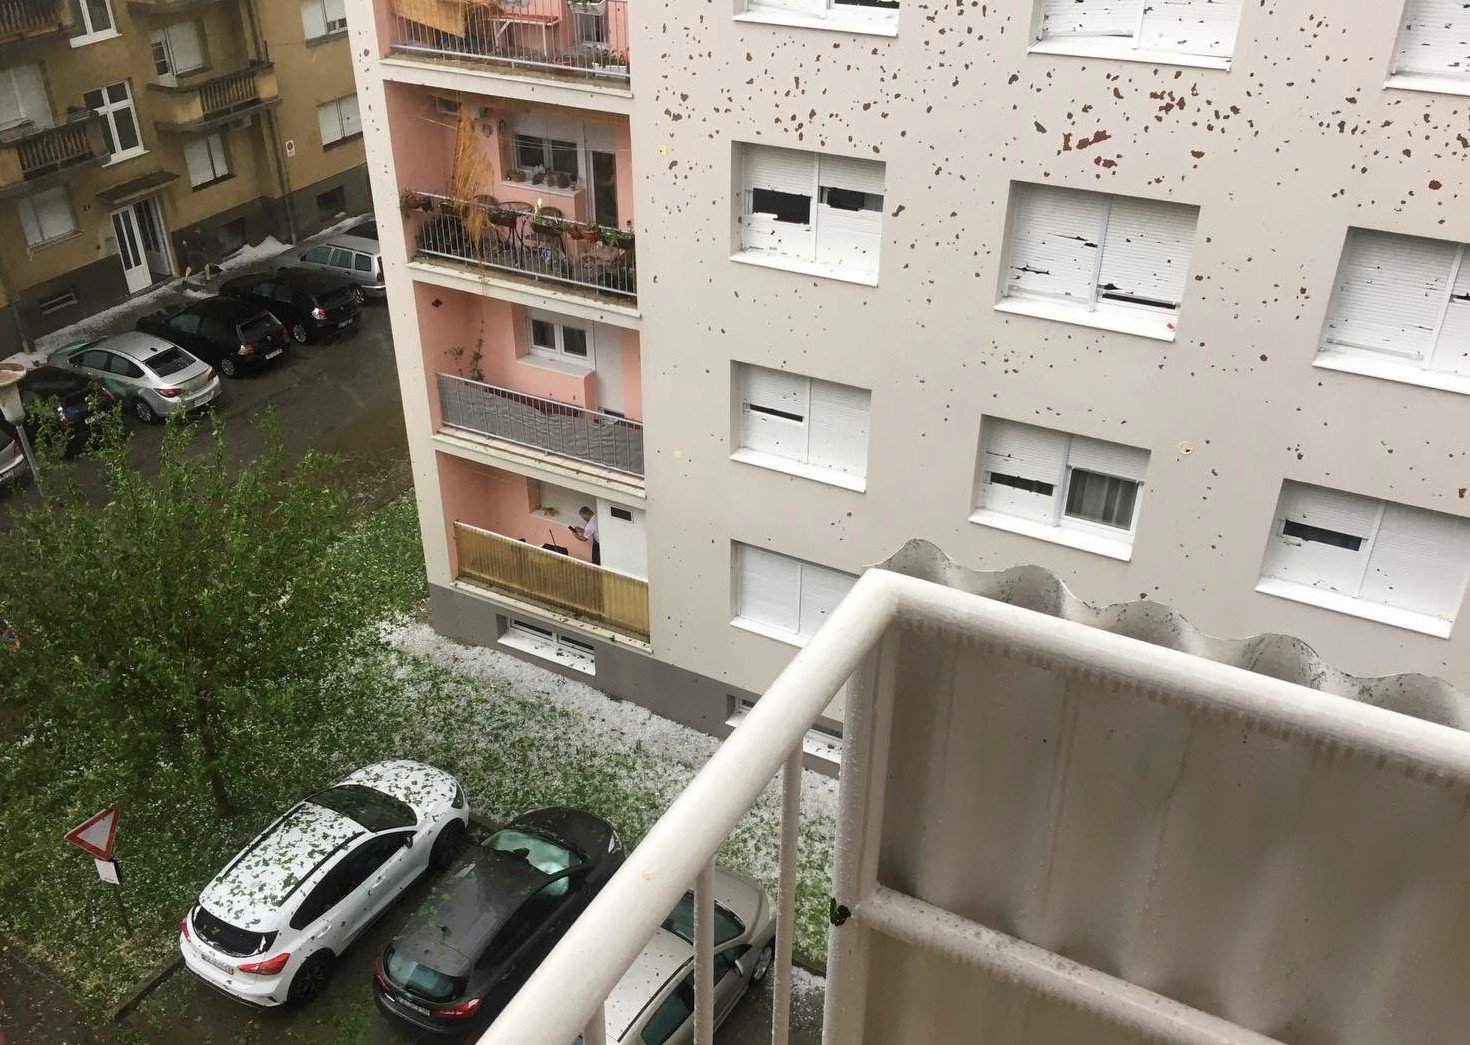
Photo: Nikola / Wikimedia Commons, CC BY-SA 4.0
- Building, contents and car cover pay for different damage, not the same thing
- A blocked gutter or an old roof can void a storm claim entirely
- Most insurers want photos within 48 hours and a claim within 30 days
Yes, in most cases your insurance does pay for hail, flood and lightning damage in South Africa. But building insurance, household contents and car insurance each cover a different part of the damage, and one habit, a blocked gutter or a roof nobody fixed, can void the whole claim.
The South African Weather Service raised its warning for KwaZulu-Natal to level 4 at midday on Tuesday 27 October 2026, running into Wednesday. Level 2 warnings covered the Eastern Cape, Mpumalanga and the lower parts of Limpopo at the same time, according to BusinessTech.
What is actually happening in KwaZulu-Natal right now?
SAWS warned of heavy downpours, hail and severe lightning across eastern KwaZulu-Natal, including areas near Hlabisa, Hluhluwe and King Shaka Airport. The service listed flooding of settlements, roads and bridges, damage to property and infrastructure, and danger to life as likely outcomes. eThekwini's Disaster Management and Emergency Services teams were placed on standby.
In the Eastern Cape, heavy rain cut off towns across the OR Tambo district, including Mqanduli, Buntingville, Ngqeleni and parts of Port St Johns, Qumbu and Tsolo, the Daily Dispatch reported. Four pupils who had gone fishing were stranded on a river island near Mqanduli after the water rose around them. Rescue teams reached and freed all four boys, SABC News and TimesLIVE reported. Eskom reported storm damage to power lines causing outages in parts of the province.
Photo: Chris Eason from London / Wikimedia Commons, CC BY 2.0
Which policy pays for which kind of storm damage?
Most storm damage in South Africa does get paid out, but the policy that pays, and the exclusion that can block the payout, changes with every type of damage. The table below lays out nine common cases, with the rule and its source in each row so you can check your own situation fast.
| Damage | Who usually pays | The catch | Source |
|---|---|---|---|
| Hail dents the roof | Building insurance | Pre-existing roof damage or neglect | Savvy Insurance, buildings exclusions guide (2026) |
| Hail dents the car | Comprehensive car insurance only | Third-party-only pays nothing | Outsurance, hail damage cover guide (2026) |
| Water comes through the door | Building insurance, storm peril | Old or unsealed doors, wear and tear | Nedbank, flood and hail blog |
| A flash flood enters the house | Building and contents insurance | Insurers define "flood" differently from rain | Savvy Insurance, buildings exclusions guide (2026) |
| Lightning fries the TV | Household contents insurance | Rarely excluded, it is a named peril | Outsurance, contents insurance guide |
| A power surge damages appliances | Contents insurance, often a separate benefit | No surge protector fitted | Rateweb, power surge claims guide |
| A tree falls on the car | Comprehensive car insurance | Third-party-only pays nothing | Pineapple, weather damage guide |
| A tree falls on the house | Building insurance | A tree you knew was rotten and ignored | Savvy Insurance, buildings exclusions guide (2026) |
| Blocked gutters cause a flood inside | Usually excluded | Poor maintenance, not sudden damage | Savvy Insurance, buildings insurance guide (2026) |
Does home insurance cover hail, storm and flood damage?
Storm, hail and flood are standard, insured perils on almost every South African building policy. That part is simple. The hard part is maintenance.
Insurers pay for sudden, unforeseen damage, not for damage that built up over months. Gradual leaks, rust, damp and poor workmanship are excluded on every policy checked for this story. Assessors now routinely photograph gutters, roof fixings and waterproofing after a storm claim, because neglected maintenance is the single biggest reason a payout gets reduced or refused.
 Read nextWhy Netflix keeps raising prices, and what every plan costs in 5 countries
So if your gutters have been blocked for a year and water backs up into the ceiling during this week's storms, the insurer can argue the real cause was neglect, not the storm. If a storm genuinely ripped tiles off a sound roof, that claim should go through cleanly.
Does household contents insurance treat lightning differently from a power surge?
Yes, and this is where many people get caught out. A direct lightning strike that fries your TV or fridge is covered under a normal contents policy as a named peril.
A power surge, the kind caused by load shedding switching back on or by a strike nearby rather than on your house, is often handled separately. Several insurers pay it only as an add-on benefit with its own limit and its own excess, and some reduce or decline the claim if you have no surge protector fitted. Check your policy schedule for the words "power surge" as a separate line, not just "lightning".
Does comprehensive car insurance pay for hail dents and flood damage?
Comprehensive car insurance covers hail, flash flood water and a falling tree or branch, because these count as "acts of nature" beyond your control.
Third-party-only and third-party-fire-and-theft policies pay nothing for weather damage. They only cover harm you cause to someone else's car, theft or fire. If your car is on a cheaper third-party plan and hail wrecks the bonnet this week, that repair comes out of your own pocket.
Photo: David DeHetre from Lawrence, KS, USA, United States / Wikimedia Commons, CC BY 2.0
Will a blocked gutter or an old roof kill my claim?
Often, yes. Every insurer guide checked for this story draws the same line: Insurance pays for sudden damage, not for damage you could have prevented by fixing something you knew was broken.
 Trending nowBootlegger data leak: The locked dashboard that was never locked
A roof patched years ago, gutters nobody has cleared, or a tree you were told was dying all weaken a claim. Fix the obvious stuff now, before the next warning, not after a rejection letter arrives.
How much will I have to pay before insurance kicks in?
Most South African building policies carry a standard excess of R1,000 to R2,500, rising to R5,000 or more in flood-prone or high-risk areas, including parts of coastal KwaZulu-Natal. Many insurers also apply a higher, percentage-based excess specifically for wind and hail claims, so a storm payout can cost you more out of pocket than an ordinary claim.
Car insurance excess for storm damage typically runs from R1,500 to R6,000, depending on the insurer and the car.
How fast do I need to report storm damage?
Fast. Most insurers expect notice of damage within 24 to 48 hours, and a full claim within 30 days, though some allow up to 90 days for paperwork. Photograph every damaged item and surface from at least two angles before you clean up or start repairs. Insurance guides agree this single step, dated photos taken within 48 hours, is the biggest factor in whether a claim gets paid in full.
What happens if my claim gets rejected?
Ask the insurer for its decision in writing, then use its own internal complaints process first. You get at least 90 days to submit a written appeal, and the insurer must respond within 45 days.
If the insurer still says no, or ignores you for more than 30 days, you can take the complaint to the National Financial Ombud Scheme, the same office that settles disputed bank refunds, which replaced the old short-term insurance ombud in March 2024 and resolves disputes for free. You have six months from the insurer's final written response to lodge that complaint, on 0860 800 900.
It is worth the call. After the 2022 KwaZulu-Natal floods, insurers paid out more than R1 billion in claims, according to the South African Insurance Association. That money went to people who reported fast, photographed everything, and pushed back when the first answer was no.
This week's storms are smaller than that disaster so far. But the same rules apply, and they reward the person who acts in the first 48 hours, not the one who waits to see how bad it gets. If your car insurance already skips hijacking cover, check your weather cover the same way, before the next level 4 warning lands on your province.
Get the stories that hit your pocket
Petrol, SARS, Eskom, grants and the news everyone is talking about. One short email every weekday at 6am.
Free. One email each weekday. Unsubscribe anytime.Latest on this
 24 Oct 2026Why a Pacific heatwave now means pricier groceries in South Africa next year
 7 Oct 2026A super El Niño is building and the ocean is acting strange
Sources9
- BusinessTech, severe weather warning escalated to level 4 (27 Oct 2026)
- SABC News, four boys stranded on Mqanduli riverbanks (27 Oct 2026)
- Daily Dispatch, flooding cuts off towns across OR Tambo district (27 Oct 2026)
- Savvy Insurance, buildings insurance exclusions guide
- Outsurance, car hail damage cover guide
- Rateweb, power surge insurance claims guide
- Genesis Insurance, first 48 hours of weather damage claims
- MyLawSA, how to complain to the National Financial Ombud Scheme
- IOL, 2022 KZN flood insurance claims exceeded R1 billion, SAIA
Keep reading
 MoneyA US deadline near 2 November could decide the fate of 500,000 South African jobs
 MoneyElvis Presley's rights owners are suing the AI company Anthropic over 274 songs
 MoneyA dropped apple crumble, a screaming kitchen, and a £13,048 award