Two Fed officials voted to raise rates, not cut them, days before the midterms
Two officials wanted the Fed to go higher, not lower, while the president wanted cuts. The chair said politics had nothing to do with any of it.
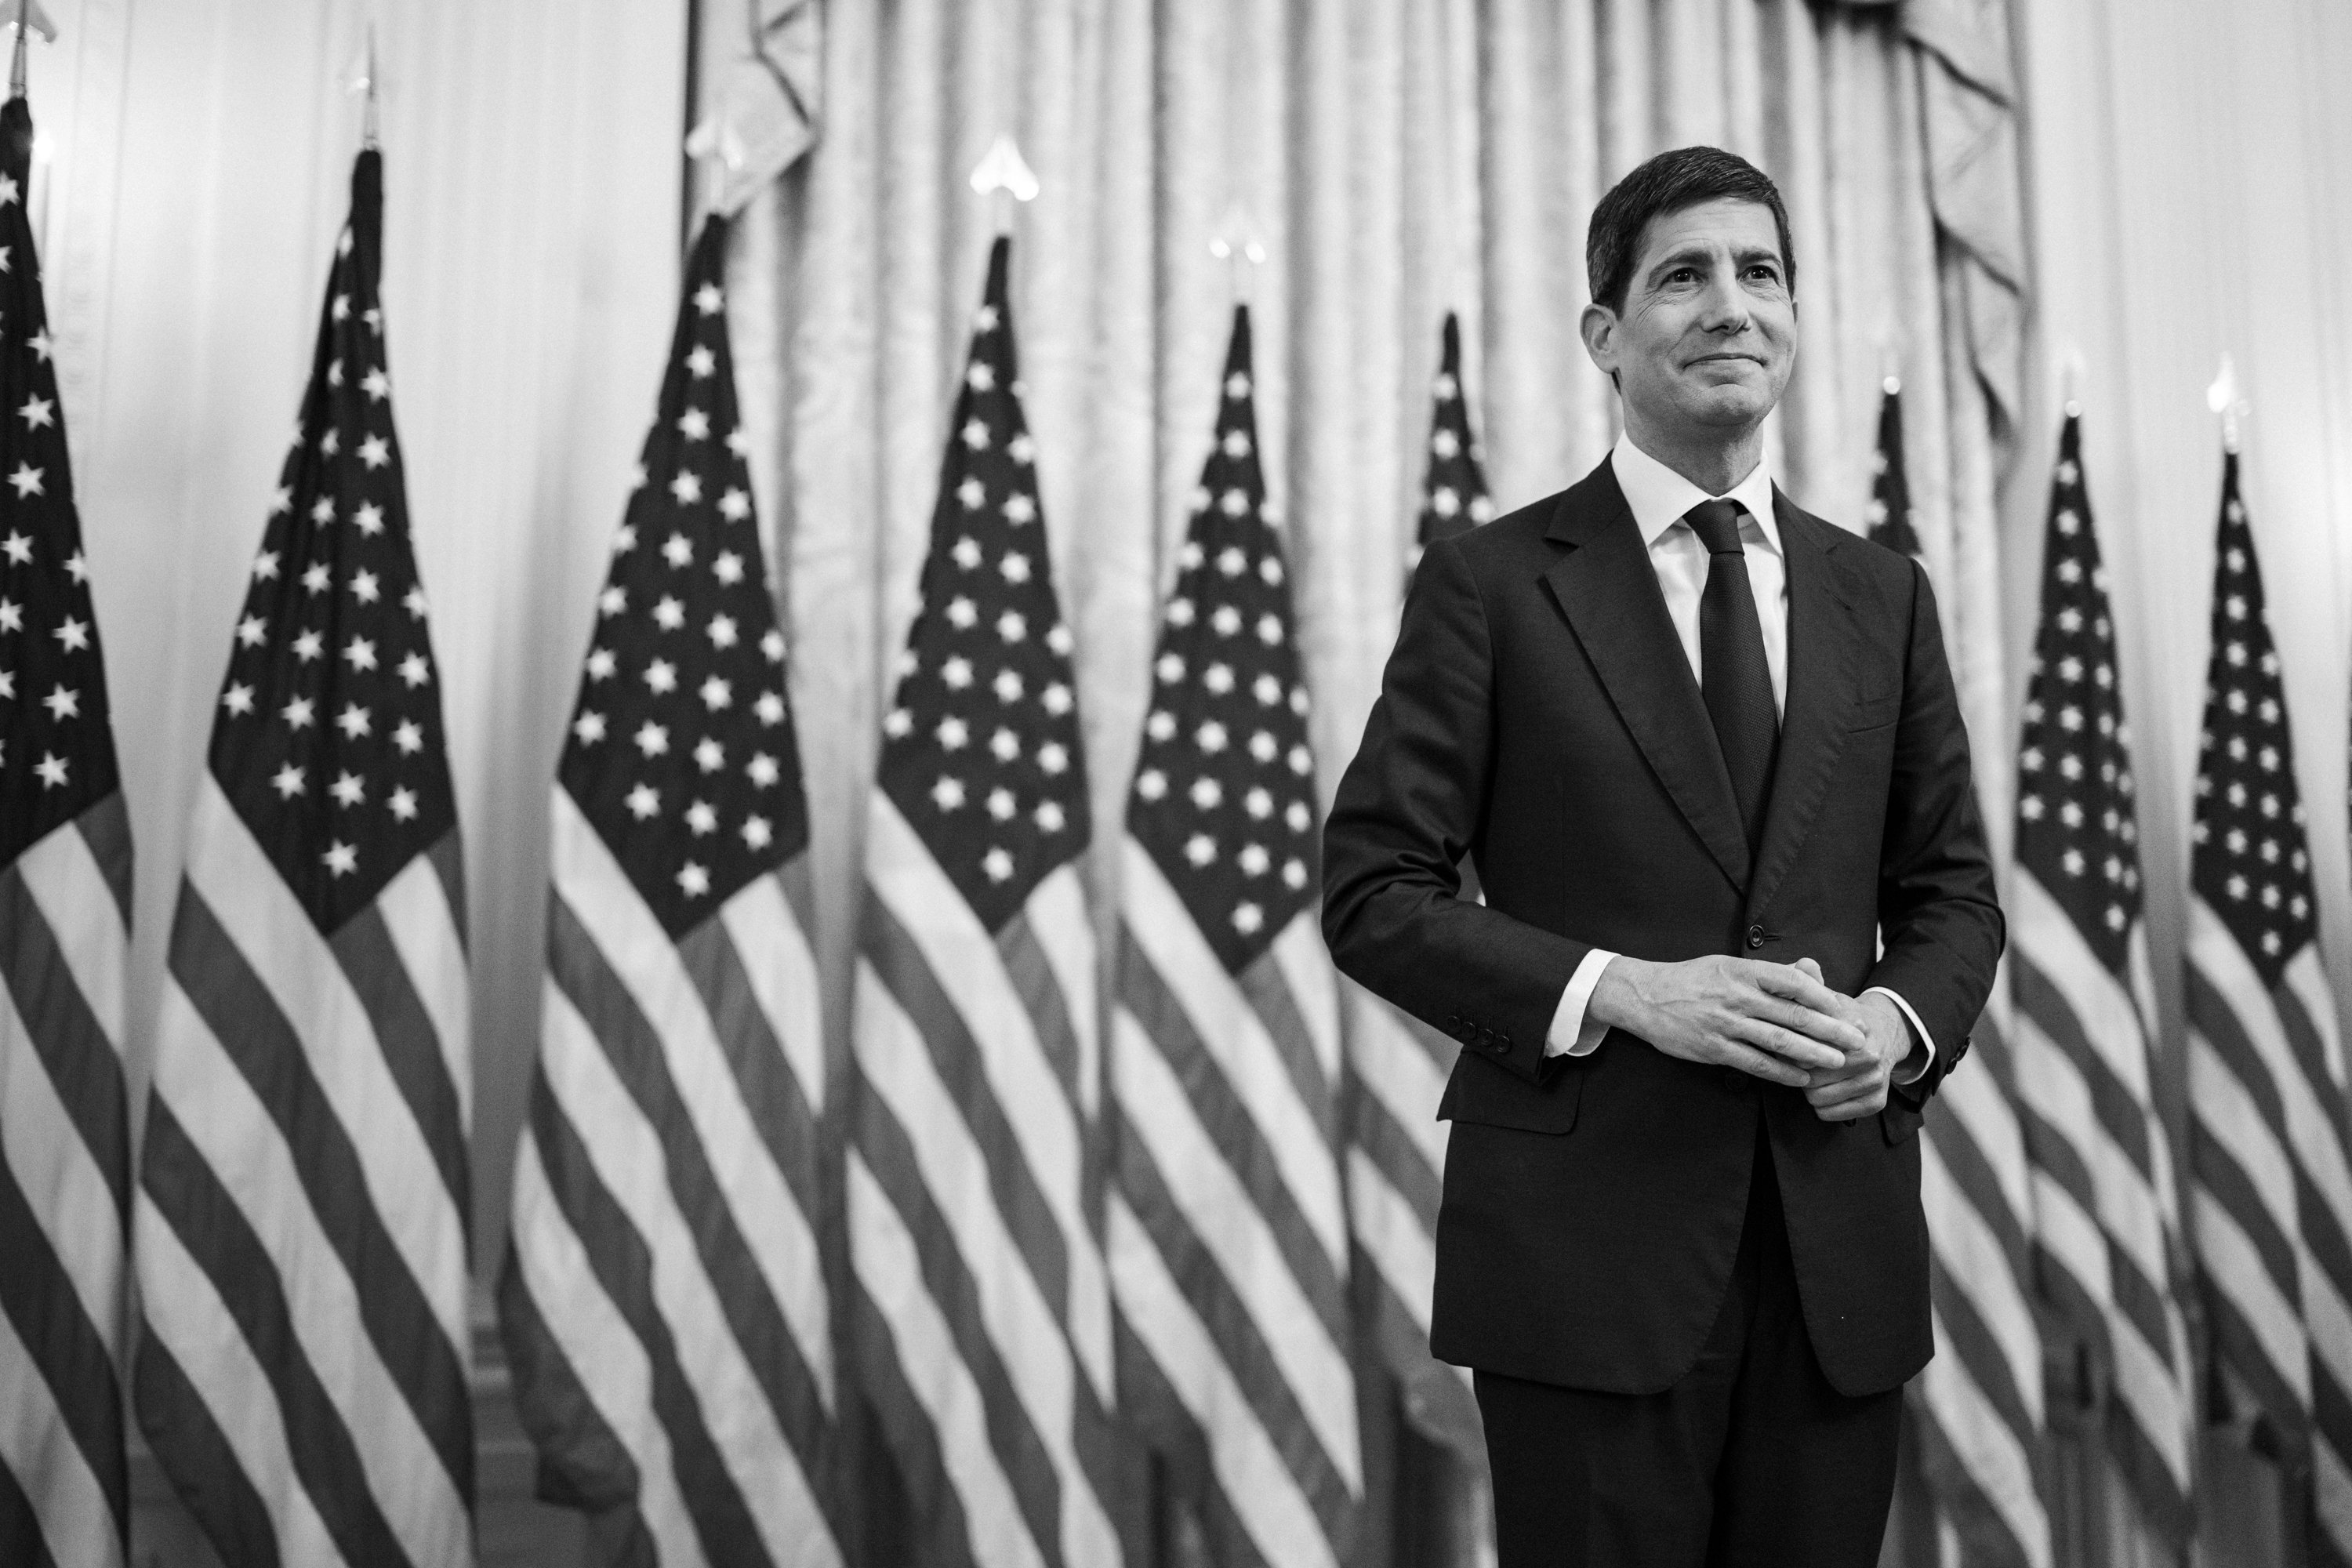
Photo: The White House / Wikimedia Commons, Public domain
- Two Fed officials voted to raise rates, not cut them, days before the midterms
- Chair Kevin Warsh said "politics played no role," unprompted
- Mortgage, savings, credit card and car loan rates all stayed exactly where they were
10-2.
That was the vote count when the Federal Reserve's rate committee met on 28 October 2026. Ten officials voted to leave interest rates exactly where they were. Two voted against it, and not for the reason you would expect.
Both dissenters wanted the Fed to raise rates again. Not cut them. This came six days before the US midterm elections, with President Trump on record for months wanting rates lower, not higher. Fed Chair Kevin Warsh stood up afterward and told reporters, without being pushed on it, that "politics played no role in this decision." When a central bank chair says that out loud before anyone asks, people notice.
Why did two Fed officials want higher rates, not lower?
The Fed's rate committee, called the FOMC, kept the target range for its benchmark rate at 3.75% to 4%, the same range it has held since early October. Fed Governor Lisa Cook and Cleveland Fed President Beth Hammack both voted no. Each one wanted a quarter-point hike instead.
Their reason was inflation. The annual rate climbed from 3.4% in August to 3.7% in September, moving the wrong way. Cook has never dissented before in her time on the board. Hammack dissented for the second time since July, both times pushing for higher rates, not lower ones.
 Read nextElvis Presley's rights owners are suing the AI company Anthropic over 274 songs
Financial reporters covering the meeting called it the most divided vote among Fed governors since 1993, a year most readers were not even born in.
What does a Fed hold actually change in your mortgage, savings, credit card and car loan?
Nothing moved on 28 October, because nothing was cut. Banks had already priced in a hold. Below is where each rate stood right before and right after the decision, each one checked on its own date.
| What it costs you | Current rate | Date it was true | Source |
|---|---|---|---|
| 30-year fixed mortgage | 7.32% | 22 Oct 2026 | Freddie Mac |
| Top high-yield savings account | 4.27% | 21 Oct 2026 | Bankrate |
| Average credit card | 19.70% | 21 Oct 2026 | Bankrate |
| 5-year new car loan | 7.13% | 27 Oct 2026 | Bankrate |
A mortgage shopper pays the same 7.32% this week as last week. A saver earning the top savings rate still earns 4.27%, more than 60 times what the national average pays, a gap that has nothing to do with the Fed and everything to do with which bank you pick. We ran the full math on what a rate cut would have meant for $10,000 in savings, and this meeting changed none of it, because the cut never came.
Why did the Fed's own chair have to deny politics played a role?
Warsh took over as Fed Chair in May 2026, sworn in at the White House by President Trump, who picked him for the job. Trump has pushed publicly for months for lower rates. Six days before an election his own party needed to win, the Fed he appointed a loyalist to chair held rates steady, while two officials pushed to tighten further.
 Trending nowLeon Lotz: The farmer the world won't believe
That is an awkward spot for a chair who owes his job to the president to be standing in. So Warsh told the room that politics played no role, said he heard no talk of the election or "what was happening in the coming week" during the two-day meeting, and moved on.
The irony: The dissent cuts against any claim that the Fed went easy to help Trump. Cook and Hammack wanted rates higher, which would hurt borrowers and help nobody heading into an election. If the vote had any politics in it at all, it is hard to say which side it was supposed to help.
Photo: Well-Informed Optimist / Wikimedia Commons, CC BY-SA 4.0
What happens at the Fed's next meeting, in December?
The committee meets again on 8 and 9 December 2026. Between now and then, a fresh inflation report lands, and if prices keep climbing the way they did in September, Cook and Hammack may not be alone next time.
A hold means every rate in that table above stays roughly where it is for at least another six weeks. Anyone carrying mortgage debt after the hike earlier this month pushed rates past 7.40% gets no relief yet. Anyone running the real math on what a 30-year home loan costs in total interest is looking at the same bill they were looking at last week.
Photo: Andykatib / Wikimedia Commons, CC0
The last time a Fed vote split this badly, Alan Greenspan was chair and the year was 1993. Thirty-three years later, the officials pulling against the chair are not asking for easier money. They are asking for less of it, with an election on the calendar and a chair who says nobody in the room was thinking about any of that at all.
Get the stories that hit your pocket
Petrol, SARS, Eskom, grants and the news everyone is talking about. One short email every weekday at 6am.
Free. One email each weekday. Unsubscribe anytime.Sources7
- Yahoo Finance live blog, Fed meeting, 28 Oct 2026
- Federal Reserve, FOMC statement, 28 October 2026
- Axios, Fed leaves rates steady as governor Lisa Cook dissents
- CNBC, five takeaways from the Fed rate decision and Warsh news conference
- Freddie Mac Primary Mortgage Market Survey, 22 October 2026
- Bankrate, current credit card interest rates, 21 October 2026
- Bankrate, auto loan rates, 27 October 2026
Keep reading
 MoneyThe FTC and 20 states say Dollar General charged more than its own shelf prices for years
 MoneyDoes insurance cover hail, flood and lightning damage in South Africa?
 MoneyVilla Vie Odyssey residents told to leave their ship home in Cambodia